My Niece Dumped Breakfast on My Plate and Called Me “Family Trash”—So I Canceled the $4,000 My Family Took Every Month
Part 1: Opening
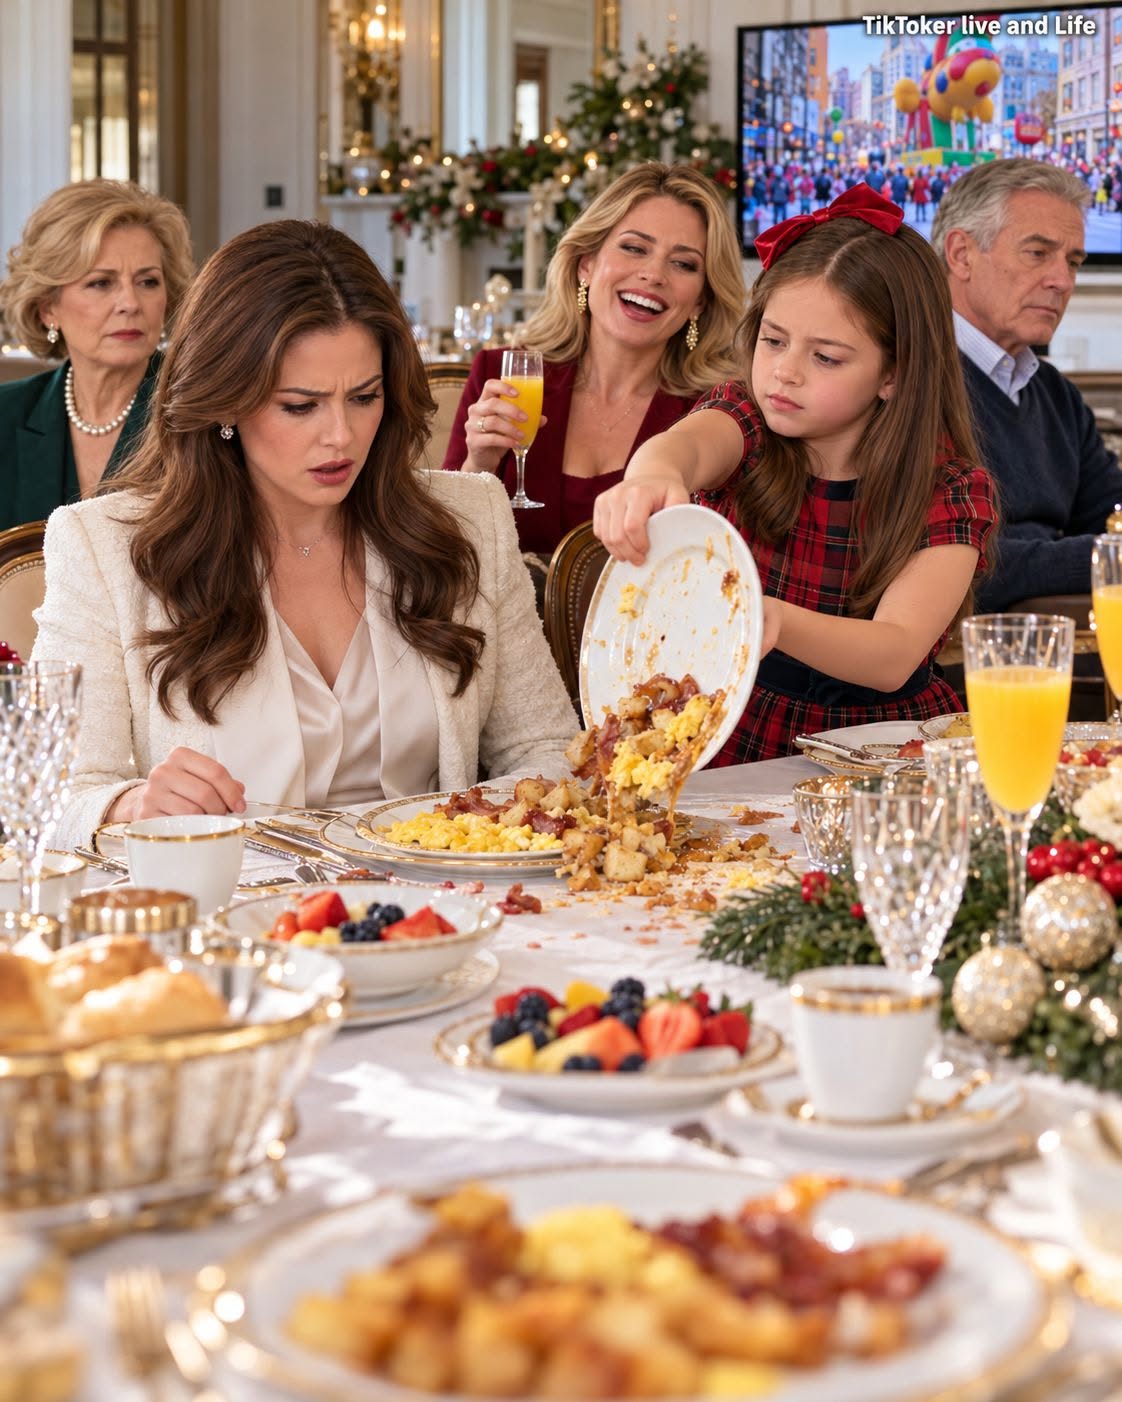
My nine-year-old niece dumped leftover breakfast onto my plate and announced, “Mom says you’re the family trash!”
My sister laughed.
My mother kept eating.
My father stared at the television.
That evening, my mother texted me, “You’re out of our lives.”
I replied, “Noted!”
By the following morning, my phone was exploding with calls from all three of them.
They weren’t calling to apologize.
They were calling because I had started canceling the $4,000 in monthly support they had relied on for years—and because, while reviewing my accounts, I had discovered a document bearing my forged signature.
My name is Whitney Carter. I was thirty-six, lived in a modest one-bedroom apartment in South Philadelphia, and worked as a financial operations manager for a regional logistics company.
I had spent nearly a decade being the person my family called whenever something went wrong.
My mother, Elaine, needed help with her phone bill.
My father, Robert, needed prescriptions paid for.
My older sister, Desiree, couldn’t qualify for a vehicle lease on her own, so she had persuaded me to put my credit on the line.
And when my parents’ Philadelphia rowhouse nearly fell into foreclosure after years of unpaid property taxes and a second mortgage, I had borrowed tens of thousands of dollars to help them keep it.
I had never expected applause.
I simply believed that if you had the ability to help your family, you should.
But somewhere along the way, helping became an obligation, and gratitude became something my family no longer considered necessary.
Desiree was especially good at making me feel guilty.
Whenever I questioned an expense, she accused me of keeping score.
Whenever I asked when she might start contributing toward her own bills, she reminded me that family was supposed to help family.
Whenever I mentioned my own financial goals, she laughed and told me I was too cautious to enjoy life.
Meanwhile, she drove a newer crossover, my parents enjoyed services they couldn’t comfortably afford, and I postponed replacing my worn winter coat because I wanted to make sure everyone else’s bills were paid.
My niece, Alana, was nine years old. I loved her, even though Desiree had increasingly encouraged her to treat me as an easy target.
I had bought Alana birthday presents, paid for her coding club, and helped cover school expenses whenever Desiree claimed she was short on money.
I had never asked the child to repay me.
I had only hoped she would learn that kindness was something to appreciate, not exploit.
Then came New Year’s brunch.
It happened at my parents’ home on a cold morning in Philadelphia. The dining room smelled of bacon, fresh coffee, and cinnamon French toast. My mother had arranged her best china on the table, and my father was watching the holiday parade on television.
Everything seemed ordinary until Alana approached me carrying a plate of leftover breakfast.
“What’s going on, sweetheart?” I asked.
She tilted the plate.
Cold potatoes, scrambled eggs, bacon, and gravy slid across my breakfast and onto the white tablecloth.
I stared at her.
Then she announced, loud enough for everyone to hear, “Mom says you’re the family trash!”
For a moment, I couldn’t speak.
I turned toward Desiree, expecting her to correct her daughter.
Instead, she took a slow sip of her mimosa.
“Come on, Alana. Let Aunt Whitney finish her breakfast,” she said casually.
She was smiling.
My mother continued eating. My father never looked away from the television.
“Desiree,” I said quietly, “did you hear what your daughter just said?”
My sister rolled her eyes.
“Don’t start acting dramatic. She’s only nine.”
“Then perhaps you should teach her how to treat people.”
My mother finally looked up.
“Children repeat things they hear. There’s no reason to ruin New Year’s Day over a childish comment.”
“Where do you think she heard those particular words?”
My father interrupted before she could answer.
“Enough, Whitney. Adults should know how to resolve disagreements without turning every little thing into a crisis.”
I glanced at the Christmas sweater I had bought him and the prescription bottle beside his coffee. I had paid for his medication two days earlier.
For years, I would have argued. I would have explained how much I had done for them and how little I expected in return.
Instead, I looked at the mess on my plate.
“You’re right, Dad. There’s no reason to ruin the day.”
I carried my ruined breakfast into the kitchen, scraped it into the garbage, rinsed the plate, and placed it in the drying rack.
Then I collected my coat.
“Leaving already?” my mother asked.
“Yes.”
Desiree laughed.
“Unbelievable. You always need attention.”
I stopped near the doorway.
“No, Desiree. I don’t.”
Nobody answered.
I walked outside without slamming the door.
The cold air struck my face, and I realized I couldn’t remember the last time my family had made me feel loved without expecting something from me.
By the time I reached my apartment, the family group chat was overflowing with complaints.
Desiree claimed I had frightened Alana.
My mother accused me of embarrassing everyone.
My father insisted that I owed them an apology for walking out.
I didn’t respond.
I made tea, changed my clothes, and sat at my kitchen table.
At 9:47 that evening, another message appeared from my mother.
“You’re out of our lives.”
My father reacted with a thumbs-up.
Desiree added a heart.
I stared at the screen for a long time.
Then I typed two words.
“Noted!”
I left the group chat.
Eight seconds later, my phone began ringing.
Desiree.
Then my father.
Then my mother.
I didn’t answer.
Instead, I opened my banking application and reviewed every recurring expense connected to their lives.
The list included the house loan, vehicle lease, insurance, family phone plan, internet service, Alana’s coding club, medical expenses, subscriptions, and countless smaller charges.
The total approached $4,000 every month.
I had been spending more money supporting people who openly disrespected me than I spent maintaining my own household.
For the first time, I saw the situation as it really was.
I wasn’t simply helping my family.
I was financing an arrangement in which they received the benefits and I absorbed the risk.
I opened the payment settings for their internet service.
A small switch controlled the automatic monthly draft.
I pressed it.
Then I began reviewing the rest.
That was when I noticed an unfamiliar entry in my financial records.
It was connected to a loan account I didn’t recognize.
And beside it was a document bearing my name.
My signature was at the bottom.
The problem was that I had never signed it.
Part 2: The Signature That Wasn’t Mine
I downloaded the document and opened it on my laptop.
The first page appeared ordinary enough: an account authorization associated with the loan I had taken out years earlier to help my parents save their house.
But the more I read, the less sense it made.
The document appeared to authorize a change in the handling of the loan, including the use of my personal financial information and an additional credit arrangement.
My name appeared beside the words authorized borrower.
At the bottom was a signature that looked like mine at first glance.
It had the same slant.
The same oversized W.
The same looping final letters.
But the signature was too neat.
I had developed a small tremor in my hand after an old wrist injury, and my actual signature had a distinctive break in the middle of my surname.
The one on the document did not.
I enlarged the image.
Someone had copied my signature from another document.
I sat motionless for several minutes.
Then I checked the date.
The authorization had been submitted six weeks earlier.
Six weeks before Alana dumped food onto my plate.
Six weeks before my mother declared me out of the family.
Six weeks before I realized that the people I had spent years protecting might have been using my financial support for something I had never agreed to.
I called the financial institution using the number listed on its official website.
After verifying my identity, I explained that I had found a document containing a signature I did not recognize.
The representative transferred me to its fraud department.
A specialist asked me several questions about the account and advised me not to sign anything further until the matter had been reviewed.
I requested copies of the original submission, the associated account records, and any documentation identifying how the authorization had been received.
I also asked that the disputed request be flagged and that any new activity requiring my authorization be reviewed carefully.
The specialist explained that the institution would need to investigate before making any determination about what had happened.
I understood.
A suspicious document was not the same thing as a completed fraud finding.
But it was enough to make me stop treating the situation as a family misunderstanding.
The next morning, I called a lawyer who specialized in consumer financial disputes.
Her name was Andrea Lewis.
I brought her the document, my original loan agreement, and several examples of my actual signature.
She studied the papers without making any promises.
“This needs to be handled carefully,” she said. “First, we establish exactly what this document was intended to do. Then we determine whether it was submitted, relied upon, or used to create any financial obligation.”
“Can you tell who signed it?”
“Not from this copy alone. We may need the original file, submission records, and possibly a forensic review.”
“What should I do about the money I’m sending my family?”
Andrea asked me to separate the voluntary payments from any contractual obligations.
“The phone bill you pay for your mother is one thing. A vehicle lease in your name is another. A loan you legally guaranteed is another still. Don’t assume you can cancel every obligation immediately just because you’re angry.”
I appreciated that she didn’t tell me what I wanted to hear.
I wanted to press a button and make every responsibility disappear.
But some agreements were legally mine, even if other people benefited from them.
So we made a plan.
I would stop new voluntary transfers.
I would cancel services that belonged to my family but were being paid from my account, following the applicable cancellation terms.
I would review every contract bearing my name before taking further action.
And I would not sign any new document presented by my relatives without independent review.
That afternoon, I created a spreadsheet.
Every payment.
Every account.
Every agreement.
Every person who had access.
The numbers were painful.
Over the previous nine years, I had paid more than $130,000 toward expenses benefiting my parents and sister. That figure included the money I had contributed toward their housing crisis, regular support, and recurring bills.
Some of that help had been freely given.
Some had been described as temporary loans.
A few payments were tied to agreements I needed to examine more closely.
I couldn’t simply declare every dollar stolen.
But I could finally see how much of my own financial security had been sacrificed without a clear plan for repayment.
At noon, Desiree arrived at my apartment.
She had called seventeen times.
I hadn’t answered.
Now she stood outside my door, wearing sunglasses and holding her phone like a weapon.
“Are you seriously cutting everyone off because of a joke?”
I opened the door but didn’t invite her inside.
“Alana dumped food on my plate and called me the family trash. You laughed.”
“She didn’t understand what she was saying.”
“Then you should have corrected her.”
Desiree sighed.
“Mom is upset. Dad’s blood pressure is up. You’re making everyone miserable.”
“I’m not responsible for managing everyone’s feelings.”
Her expression hardened.
“So you’re really canceling the money?”
“I’m reviewing the arrangements and ending the voluntary support I can legally stop.”
She stared at me.
“You can’t do that.”
“I can stop paying bills that I agreed to pay voluntarily.”
“What about the house?”
“I’m reviewing the loan and the documents connected to it.”
For the first time, her confidence faltered.
“What documents?”
I watched her carefully.
“The ones bearing my signature.”
Her face changed.
It was subtle, but I saw it.
A momentary tightening around her mouth.
A pause before she spoke.
“What are you talking about?”
I didn’t answer.
She stepped closer.
“Whitney, whatever you’ve found, don’t turn this into something it isn’t. Mom and Dad have enough problems.”
“Then you shouldn’t have anything to worry about.”
Desiree looked away.
“I have to go.”
She left before I could ask another question.
I closed the door and wrote down the time of her visit.
That evening, Andrea called.
The institution had confirmed that the disputed authorization had been submitted and was associated with a request to change the handling of the existing family loan.
It had not yet confirmed who had submitted it.
The institution had also identified a separate inquiry involving my credit information.
Andrea asked me to obtain the complete records before drawing conclusions.
“We need to know what they were trying to accomplish,” she said. “And we need to distinguish an attempted authorization from any actual change to your obligations.”
I looked at the document on my laptop.
The signature was mine in appearance only.
But the question was no longer simply who had copied it.
It was why.
And the answer was hiding in the financial records my family had never expected me to examine.
Part 3: What They Were Hiding
Over the next two weeks, I stopped treating the problem as a family dispute and began treating it as a financial investigation.
Andrea sent formal requests for the relevant records.
I obtained my credit reports, checked the accounts connected to my identity, and contacted the institutions involved to dispute any information I did not recognize.
I changed passwords, enabled additional account security, and removed any unnecessary access that other people had been given.
I also created a separate account for my own expenses.
I didn’t transfer assets to hide them or stop payments that I was legally required to make.
I simply stopped giving my family new access to my money.
The first discovery came from the loan records.
The document bearing my forged signature had been submitted as part of a request to modify the existing arrangement and extend additional credit against the property my parents owned.
The request had not been fully approved.
However, the supporting file contained a financial summary showing the amount of debt still associated with the house, the estimated property value, and a proposed use for additional funds.
The proposed use was not a roof repair or overdue property taxes.
It was a cash-out refinancing arrangement.
And the person listed as the primary contact was Desiree.
I stared at the page.
My sister had been trying to arrange additional financing using a loan connected to the house I had helped save.
My name appeared in the supporting documents because I had provided financial assistance years earlier.
But I had never agreed to authorize the new request.
Andrea examined the records.
“This raises serious questions,” she said. “But we still need the original submission history and the institution’s findings before we can say who created the document.”
“Could my parents have known?”
“They may have. They may not have. We shouldn’t guess. We’ll ask for the records that establish what happened.”
The second discovery came from a folder of emails attached to the loan file.
One message from Desiree to a mortgage broker described me as a family member who was “already committed to supporting the property.”
Another stated that I would “sign whatever was necessary once the paperwork was explained.”
I had never written those words.
I had never agreed to additional borrowing.
And I had certainly never authorized anyone to represent that I would.
I printed the emails and gave them to Andrea.
She advised me not to contact the broker or accuse any particular person before the evidence had been reviewed.
Instead, she sent a formal notice disputing the authorization and requesting that the application be preserved for investigation.
The next morning, my father called.
“Whitney, we need to talk.”
“About what?”
“Your mother says you’ve contacted the bank.”
“I disputed a document bearing my signature that I didn’t sign.”
He went quiet.
Then he said, “It was just paperwork.”
“What paperwork, Dad?”
“The refinancing documents.”
“Did you know my signature was on them?”
Another pause.
“I thought Desiree had talked to you.”
“She didn’t.”
“Maybe there was a misunderstanding.”
“Then why did she tell the broker I would sign whatever was necessary?”
He exhaled sharply.
“You know your sister. She gets ahead of herself.”
“That doesn’t explain why my signature was used.”
“We were trying to make things easier for everyone.”
“By borrowing against the house and involving me without my permission?”
“We needed money.”
“So did I, Dad. I needed money to pay the loan I already took out to help you.”
He didn’t answer.
I waited.
Finally, he said, “Your mother is going to be devastated if this becomes a legal matter.”
“I’m not responsible for protecting anyone from the consequences of a document they submitted without my authorization.”
I ended the call.
For the first time, I understood how my family had managed to keep me financially entangled for so long.
Whenever I questioned something, they invoked loyalty.
Whenever I asked for records, they accused me of being suspicious.
Whenever I hesitated, they reminded me how much they had sacrificed for me when I was younger.
The emotional pressure had made me reluctant to ask questions.
And that reluctance had made it easier for them to assume I would continue paying.
Three days later, Andrea received a response from the institution.
Its preliminary review indicated that the disputed signature did not match the original signature on file and that the request had been submitted through an account associated with Desiree’s email address.
That did not, by itself, establish who had physically signed the document or whether anyone else had participated.
But it was enough for the institution to refer the matter for further review and keep the disputed request on hold.
Andrea advised me that I could make a formal report if I wished.
I decided to do so.
I provided the documents, the emails, the account records, and a written statement explaining that I had not authorized the request.
I did not exaggerate what I knew.
I did not claim to know who had forged the signature.
I simply reported what the records showed and allowed the investigation to proceed.
Meanwhile, I began separating myself from the family’s voluntary expenses.
I canceled the family phone plan after arranging a transition period so that no one would lose access to an essential number without warning.
I stopped paying Desiree’s coding-club fees for Alana, giving her time to arrange another payment method.
I removed my credit card from subscriptions and services that belonged to my parents.
The vehicle lease required a separate review because my name was on the agreement. I couldn’t simply abandon it, so Andrea helped me explore the available options with the leasing company.
The $4,000 monthly support did not vanish overnight.
But the amount I voluntarily contributed began to decrease, and I no longer agreed to new financial commitments.
My family reacted as though I had committed a betrayal.
Desiree sent messages accusing me of punishing Alana.
My mother said I was destroying the family over paperwork.
My father asked whether I would really let my sister face financial trouble alone.
I replied only when a response was necessary.
“I love Alana. I will not use money to punish her. But I will not pay expenses I have not agreed to pay, and I will not accept financial obligations created without my permission.”
Then I stopped arguing.
Several weeks later, the formal review reached a more significant stage.
The institution confirmed that the disputed authorization had not resulted in the additional credit being issued. Its records showed that the request had been initiated using credentials associated with Desiree’s account, while the signature itself had been uploaded as a supporting document.
The institution could not establish from its own records exactly who had written or copied the signature.
That question remained part of the investigation.
I didn’t receive a dramatic confession.
No one burst into my apartment and admitted everything.
Instead, there were formal interviews, additional document requests, and a growing understanding that the matter could not be dismissed as a harmless misunderstanding.
My parents eventually acknowledged that they had known Desiree was pursuing refinancing.
They said they believed she had arranged the necessary permissions.
They insisted that they had not intended to create a problem for me.
I told them that intention did not replace authorization.
Desiree denied forging my signature, saying she had relied on information supplied by the broker and assumed I had already agreed.
I did not accept that explanation as proof of innocence or guilt.
The records would have to speak for themselves.
The investigation continued, and I let the appropriate people handle it.
What I could control was my own life.
I rebuilt my budget around my actual income and obligations.
I started saving again.
I replaced the winter coat I had postponed buying for three years.
I took a weekend trip without calculating how much money I could have sent to my parents instead.
And I learned that financial boundaries were not a declaration that I no longer loved my family.
They were a declaration that love did not grant anyone permission to use my name, credit, or money without my consent.
Months later, Alana sent me a handwritten card.
Her spelling was uneven, and one corner was covered in pink glitter.
It said:
“Dear Aunt Whitney, I’m sorry I was mean to you. Mom said something bad and I repeated it. I know that doesn’t make it okay. I hope we can have breakfast together again.”
I read it twice.
I didn’t blame a nine-year-old for the adults’ financial decisions.
I didn’t ask her to explain what she knew about the disputed documents.
I called Desiree and asked whether Alana could visit me for an afternoon, with the arrangements agreed upon by the adults.
She could.
When Alana arrived, I made pancakes.
She sat at my small kitchen table, looking nervous.
“Are you mad at me?” she asked.
“I was hurt by what happened,” I said. “But I’m glad you apologized.”
She stared at her plate.
“Mom says you don’t help us anymore.”
I took a breath.
“I still love you, Alana. But adults need to make their own decisions about money, and they need to be honest about it. You don’t have to fix any of that.”
She nodded.
Then she asked whether she could have another pancake.
I smiled.
“Of course.”
It wasn’t a magical reconciliation. It didn’t erase the financial dispute or restore the trust I had lost in my parents and sister.
But it was a beginning that didn’t require me to buy anyone’s affection.
As for my mother, she eventually sent a short message asking whether we could talk.
I didn’t answer immediately.
I wanted any future conversation to begin with honesty, not another demand for support.
The family that had once depended on my silence was learning that I would no longer confuse being useful with being loved.
I never learned every detail of what Desiree had intended when she submitted the refinancing request. The investigation and any resulting legal decisions would have to establish responsibility.
But I learned enough to change my life.
I learned that a forged signature is not a family misunderstanding.
I learned that a loan I voluntarily took out years ago does not give anyone permission to create a new obligation in my name.
And I learned that I could love my niece without funding every decision her mother made.
On the next New Year’s Day, I sat at my own kitchen table with a cup of coffee and a plate of French toast.
There was no expensive china.
No family parade on television.
No one waiting for me to pay a bill before deciding whether I belonged.
My phone remained quiet.
For the first time in years, I wasn’t waiting for my family to approve of me.
I was building a life that no longer required their approval.
They had called me the family trash.
They had told me I was out of their lives.
And they had assumed I would keep paying because that was what I had always done.
But the most important discovery wasn’t the forged signature.
It was the truth behind it.
My family had mistaken my generosity for permission, my silence for consent, and my love for an unlimited financial guarantee.
They were wrong.
I could care about them without financing their lives.
I could love Alana without accepting her mother’s behavior.
And I could refuse to sign away my future simply because someone shared my last name.
The document had revealed a serious problem, and I would let the proper process determine what happened next.
My own decision, however, was already made.
I would never again pay for the privilege of being treated like I belonged.