My Husband Used My Identity to Put My Grandmother’s House at Risk—Then His Own Hidden Files Revealed a Much Bigger Financial Scheme
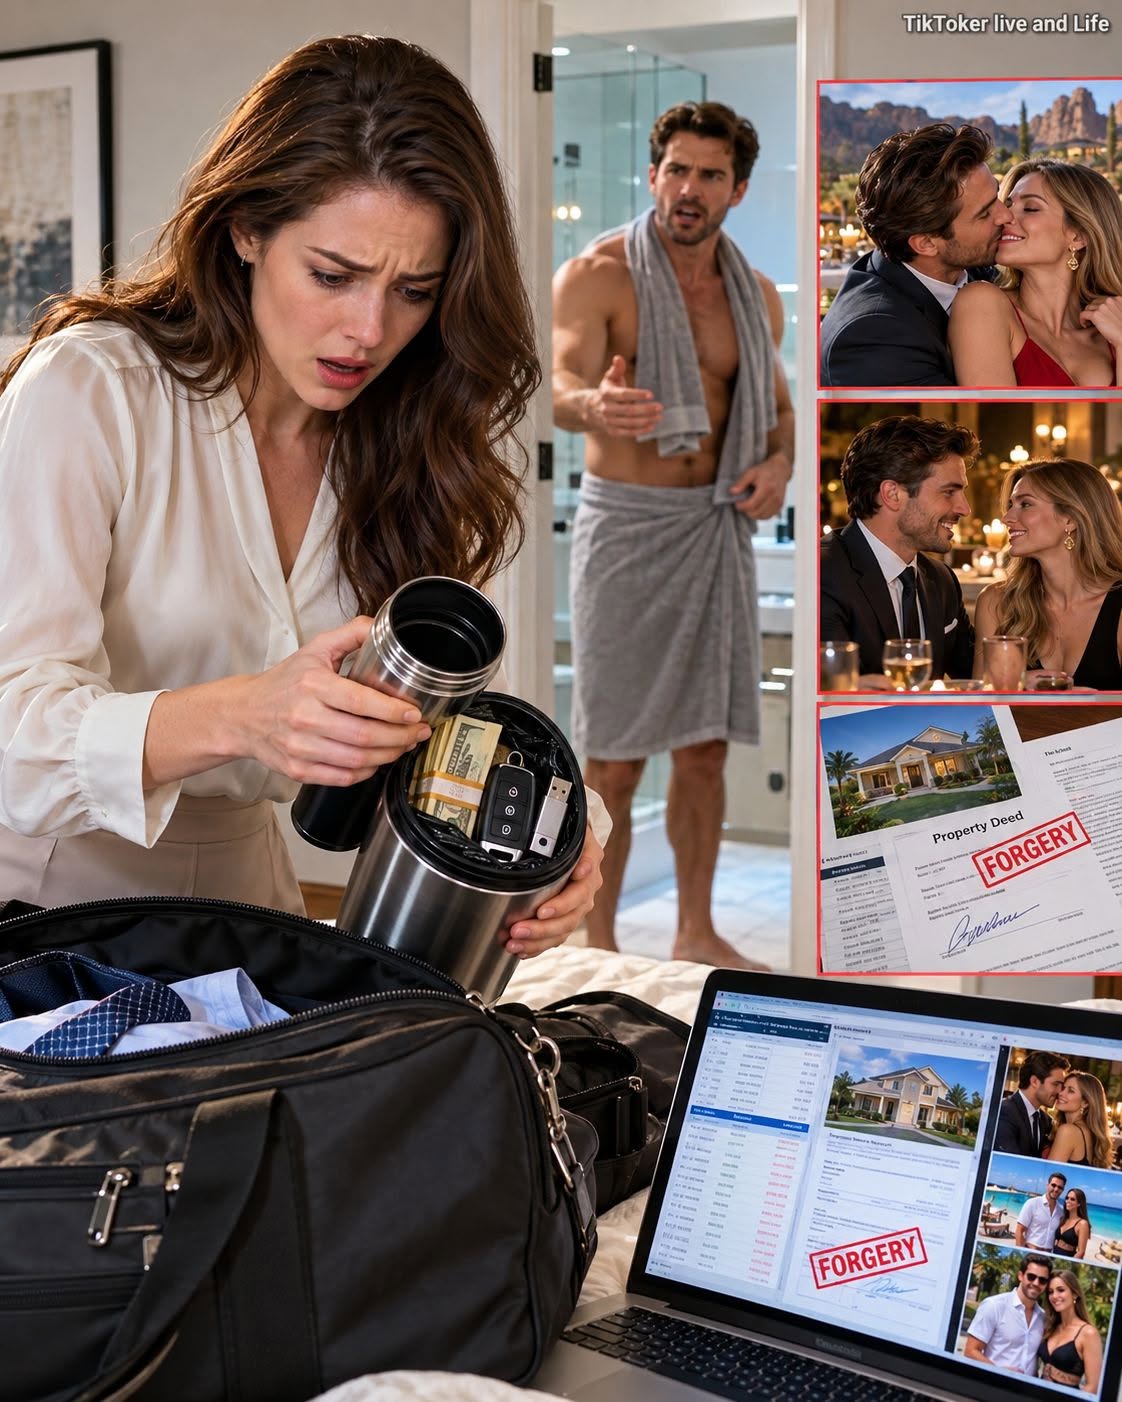
Part 1: Opening
Justin called me at 8:17 the following morning.
“Tell me you haven’t touched the original drive again.”
“I copied the files and put everything back exactly where I found it.”
“Good. Don’t delete anything, don’t try to access his accounts, and don’t contact anyone mentioned in those folders yet.”
His voice was unusually serious.
“What did you find?”
“I’m still examining the copies. Some of the files appear to have been altered, and there are signs that the drive was deliberately organized to conceal the relationships between several transactions. I need to distinguish original records from copies and determine what can be verified.”
I stared at the kitchen wall.
“Justin, my signature is on a document transferring my grandmother’s house to Mason.”
“Then you need a property attorney immediately.”
“I also found evidence of millions of dollars moving through companies that appear to have no legitimate business purpose.”
“That’s potentially a separate investigation. Don’t mix the two issues. Protect your property first, and let qualified investigators establish what the financial records mean.”
I had spent seven years believing that if I worked hard enough, budgeted carefully enough, and remained patient enough, Mason and I would eventually build the life we wanted.
Now I was learning that I might have been financing a life he had built with someone else.
Justin agreed to preserve the files and examine their metadata. He would not promise that every spreadsheet was genuine or that every transaction proved a crime. He explained that digital evidence needed to be authenticated and connected to independent records before it could support any conclusion.
That afternoon, I met with Elaine Brooks, a property attorney recommended by a trusted colleague.
I brought my grandmother’s will, the probate documents, the deed, the suspicious power of attorney, and the loan paperwork I had copied from Mason’s drive.
Elaine examined each document carefully.
“Your grandmother’s will left the property to you?”
“Yes.”
“And the deed currently recorded with the county?”
“Still shows me as the owner, as far as I know.”
“Then we need to obtain a current certified copy and determine whether anyone has filed a transfer or recorded a lien. A forged power of attorney does not automatically transfer ownership, but a fraudulent document can still create serious problems if someone has used it to obtain a loan.”
She asked whether I had ever signed anything authorizing Mason to borrow against the house.
“No.”
“Have you ever agreed to make it collateral for his business?”
“Never.”
Elaine nodded.
“We’ll notify the relevant parties that the authority is disputed, preserve your records, and determine what legal protections are available. Don’t stop making any legitimate payments until we understand the loan and your obligations. We need to prevent damage without accidentally creating a different problem.”
I left her office with a list of tasks and the first sense of control I had felt in months.
The county records showed that my name remained on the deed. However, a document purporting to grant Mason authority to act on my behalf had been submitted to support a commercial loan application.
The lender had accepted the paperwork provisionally and advanced funds to Mason’s business.
My grandmother’s house had not simply been threatened by an idea in a folder.
Someone had used my identity to put it at risk.
Elaine contacted the lender’s fraud department and requested an immediate review. She also advised me to notify my homeowner’s insurer and secure every account connected to the property.
Meanwhile, Justin continued examining the copied drive.
Three days later, he called again.
“I’ve identified something important.”
I sat down.
“What?”
“The files include a spreadsheet that appears to reconcile transfers between the development firm, two intermediary companies, and an account associated with Mason. Some of the figures match entries in the bank statements. But I can’t independently verify the source of every file, so this is a lead, not a final conclusion.”
“Does it show he took the money?”
“It shows transactions that deserve investigation. The company’s own bank records will be necessary to establish what happened.”
“There’s more,” he continued. “The property documents and the financial spreadsheets were stored alongside messages discussing how to make the transfers look like legitimate expenses.”
I closed my eyes.
“Can you tell who wrote them?”
“Some messages appear to come from accounts associated with Mason and another person. But account ownership and authorship aren’t the same thing. We’ll preserve what we have and let investigators obtain the underlying records.”
I thought of Chloe.
“Does her name appear?”
“Yes. In the communications and in several expense records.”
I gripped the phone.
“Is she involved?”
“I can’t establish that from her name appearing in files. She may have knowledge, or she may have been copied on something without understanding it. We shouldn’t assume.”
His caution was sensible.
But it didn’t make the photographs any easier to forget.
For three years, Mason had told me we couldn’t afford fertility treatments. He had told me the housing market was unstable and that we needed to be careful. He had complained about grocery bills while spending money on resorts and jewelry.
I had believed we were struggling together.
Now I wondered how much of our marriage had been built on information he had deliberately withheld.
Then Justin said something that changed the direction of the investigation.
“The drive also contains a folder of scanned communications with a notary. One message says the notary was asked to verify your identity without meeting you.”
My stomach tightened.
“Can we prove that happened?”
“Not yet. We need the notary’s records and a statement. But the message is specific enough to give the authorities a clear lead.”
I looked toward the hallway, where Mason’s suitcase had stood the morning he left.
He had packed cash, keys, and a flash drive inside an empty coffee thermos.
He had thought he was hiding his secrets.
He had no idea that his own attempt to conceal them had brought me to the people who could investigate them.
Part 2: Body
Elaine filed a formal notice disputing the power of attorney and the loan documents connected to my property.
She also helped me obtain a certified copy of the current deed and a complete record of the documents submitted to the county.
The deed still identified me as the sole owner.
The suspicious power of attorney, however, had been included in the lender’s file. It purported to authorize Mason to act on my behalf in financial matters, including the use of my property as collateral.
The notary’s name was printed beneath my forged signature.
Elaine contacted the notary through the appropriate channels and requested the journal entry and supporting identification records. The notary initially responded that the transaction appeared in the office’s system but could not immediately locate the original appointment notes.
That uncertainty was troubling.
It was not proof of wrongdoing by the notary, but it was another matter that needed to be examined.
At Elaine’s recommendation, I also filed a report concerning the suspected forgery and unauthorized use of my identity.
The officer who took my statement asked me to explain how I had obtained the documents.
I told him about the thermos, the copied drive, and Justin’s examination.
He listened carefully.
“Do you still have the original device?”
“Yes. I returned it to the thermos and haven’t touched it since.”
“Keep it secure. Don’t try to access it again. We’ll discuss how it can be collected and examined properly.”
I agreed.
I also provided the location of the copied files and the names of the companies appearing in the financial records.
The officer explained that the alleged property fraud and the suspected embezzlement might involve different investigators. He could not promise that the files would establish every allegation, but he could refer the information for review.
I left the station feeling strangely calm.
For the first time, I was not trying to convince Mason to tell me the truth.
I was giving the truth, whatever it turned out to be, a chance to be established independently.
The lender’s fraud department contacted Elaine the following week.
Its preliminary review found that the loan application included a power of attorney that the lender had not independently verified with me. The lender agreed to place a temporary hold on further advances and to investigate the authorization and collateral documents.
Elaine warned me that this did not automatically release the house from the dispute. The lender would need to determine what had happened, and we might have to seek additional court relief.
But it prevented the situation from getting worse while the records were reviewed.
I changed the locks, secured the original property documents, and removed Mason’s access to every financial account I controlled. I also froze new credit applications where possible and reviewed my credit reports for unfamiliar accounts.
Then I did something I had avoided for years.
I looked honestly at our finances.
The household budget showed that I had paid the mortgage, utilities, groceries, and most of our shared expenses. Mason had repeatedly described his contributions as essential to keeping us afloat, but his deposits had become increasingly irregular.
I had accepted that explanation because he worked in real estate and claimed that his income depended on commissions.
Now I found payments from our joint account that had no obvious household purpose.
Some went to hotels.
Others went to luxury retailers.
Several were transfers to accounts I did not recognize.
I recorded each transaction and gave the list to Elaine rather than attempting to investigate the recipients myself.
The next major development came from the development firm where Mason worked.
An investigator from the company contacted me after receiving a referral about the suspicious transactions. The company had begun reviewing its accounts after discovering inconsistencies in project expenses and vendor payments.
The investigator asked whether I had any documents related to Mason’s financial activities.
I explained that I had already provided information to law enforcement and would cooperate through the proper channels. I did not send confidential company records to anyone privately.
A week later, the investigator confirmed that several transactions identified in the spreadsheet also appeared in the company’s own accounting system.
The company had found payments to vendors whose addresses and ownership details required further examination. It had also identified transfers that did not appear to match approved project expenses.
Mason was placed on administrative leave while the company conducted its internal review.
That was the first time I understood that the matter was larger than my marriage.
But the company did not declare him guilty, and neither did I. Its investigation was ongoing, and the financial records had to be reconciled with contracts, approvals, and bank statements.
Meanwhile, Chloe’s role remained unclear.
The company confirmed that she had approved certain administrative expenses within her assigned duties, but it had not yet determined whether she knew that any transactions were improper.
I wanted to believe she had been an innocent bystander.
Then Justin found another file.
It was a message exchange between Mason and an account that appeared to belong to Chloe. In it, they discussed a luxury trip and a payment described as a business-development expense.
Another message referred to the house as “the backup collateral.”
I stared at the screen.
“Does this prove she knew about the loan?”
“No,” Justin said. “It suggests she may have known about the property arrangement, but we need context and authentication. A message can be incomplete or misleading. The investigators should obtain the original communications.”
I understood.
The affair was already a betrayal. I didn’t need to turn uncertainty into an accusation.
But the house was different.
My grandmother had left it to me after years of saving. I had cared for her there during the last months of her life, and she had made it clear that the property was meant to give me security.
Mason had taken something deeply personal and treated it as a financial instrument he could use without asking.
I met with Elaine again.
“What happens if the lender tries to enforce the loan?”
“We will challenge the validity of the authorization and any lien based on it. The outcome will depend on the evidence and the applicable law. The lender’s knowledge and conduct may also matter.”
“Could I lose the house?”
“I can’t promise you won’t face legal or financial complications. But you have important evidence: the deed, the absence of a valid authorization, the disputed signature, and records that may show how the documents were submitted. We’ll pursue every available remedy.”
I appreciated that she didn’t offer false reassurance.
For years, Mason had used confidence as a substitute for truth. I no longer wanted comforting promises. I wanted facts.
The notary’s records eventually arrived.
They showed that the appointment associated with the power of attorney had been recorded as a remote signing. But the verification documents contained inconsistencies, including an identification image that did not match the format used by the issuing authority at the time.
The notary told investigators that a third-party service had arranged the appointment and supplied the identification materials. The notary denied knowingly certifying a forged signature and cooperated with the review.
Investigators were still working to determine who had supplied the documents and whether the notary had followed all required procedures.
Elaine used the records to strengthen the challenge to the loan.
Then, one evening, Mason called.
I watched his name appear on my phone for several seconds before answering.
“Where have you been?” he demanded.
“Home.”
“You’ve been talking to people about my business.”
“I reported suspected forgery involving my property.”
“You had no right to interfere with my work.”
“My signature is on a power of attorney I never signed.”
He went silent.
Then he lowered his voice.
“You don’t understand what you’re looking at.”
“Then explain it.”
“I was going to tell you.”
“When?”
“After everything was settled.”
“After you used my house as collateral?”
“It’s a temporary arrangement. The money was going to come back.”
“From where?”
He didn’t answer.
I continued.
“Did you forge my signature?”
“I never thought you’d understand the situation.”
“That isn’t an answer.”
“I’m trying to protect us.”
“From what, Mason?”
He exhaled sharply.
“You’re turning this into a disaster.”
“No. I’m asking why my name is on documents I never signed.”
He began talking faster, explaining that the real estate market had become unpredictable, that the company was under pressure, and that he had taken steps to prevent a financial collapse.
I listened.
Then I asked, “And Chloe?”
Silence filled the line.
“What about her?”
“The photographs. The trips. The expenses.”
He said nothing for so long that I thought the call had disconnected.
Finally, he muttered, “That has nothing to do with the house.”
“It has everything to do with the money you told me we didn’t have.”
“You’re making assumptions.”
“I found the receipts.”
He tried to change the subject, but I refused to follow him into another argument.
“Any further communication about the property or finances can go through Elaine.”
“Are you threatening me?”
“No,” I said. “I’m setting a boundary.”
I ended the call.
For the first time in seven years, I didn’t feel the need to call him back and make sure he wasn’t angry.
Part 3: Conclusion
The following months were difficult, but they were no longer confusing.
The lender’s review and the property proceedings continued in parallel with the criminal investigation. Elaine challenged the loan documents and sought to prevent the disputed collateral arrangement from being enforced while the case was unresolved.
The court ordered the relevant parties to preserve the records and restricted further action against the property while the validity of the authorization was examined.
That order did not decide every issue, but it gave me time to protect my position.
The company’s investigation also advanced.
Its auditors traced a series of payments through intermediary vendors and compared them with approved contracts, invoices, and bank transfers. Some payments were legitimate business expenses. Others lacked the supporting documentation the company required.
Investigators found that several transfers ultimately reached accounts associated with Mason or entities he controlled. They also identified transactions that appeared to have been disguised as vendor payments.
The amounts were substantial, but the company did not treat every suspicious entry as proven embezzlement. It provided the records to the authorities, who continued examining the transactions and interviewing relevant people.
Chloe was interviewed separately.
The evidence showed that she had participated in some communications about expenses and had received certain benefits paid for through accounts under review. Whether she understood the source of every payment became part of the investigation.
I refused to speculate about what she knew.
I had seen the photographs. I knew the affair had been going on for years. But the question of her involvement in the financial scheme required evidence beyond the fact that she had been Mason’s lover.
Mason’s employment ended after the company’s internal review and the discovery of serious discrepancies in his work. The company referred the findings to law enforcement and pursued recovery of funds it believed had been improperly transferred.
He hired an attorney and disputed parts of the allegations.
Several months later, the prosecutor’s office filed charges arising from the suspected financial misconduct and the alleged use of forged property documents. The charges were allegations, not a final judgment. Mason entered a plea through his attorney, and the case moved through the court system.
For the first time, he had to answer questions about his decisions to people he could not intimidate into silence.
The property case took longer.
The lender initially argued that it had relied on the documents submitted with the loan application. Elaine responded that I had never authorized Mason to use my property and that the disputed signature and verification records undermined the claimed authority.
After reviewing the evidence and the applicable law, the court determined that the purported power of attorney did not give Mason authority to pledge my house. The lien based on that authorization was set aside, subject to the terms of the final order.
The lender and other parties continued resolving the financial consequences of the invalid loan arrangement, but my property was no longer available as collateral under the forged authorization.
I went to the house alone that evening.
I stood in the living room and looked at the shelves where my grandmother’s books used to sit. I had brought several of them with me when I inherited the property, and they were still there, arranged exactly as I had left them.
For months, I had feared that Mason’s decisions might cost me the one place that had always felt separate from his control.
Now I could finally breathe.
The divorce was not simple.
Mason wanted to argue that the marriage had failed because I had chosen to involve lawyers and investigators instead of discussing the problems privately.
I had heard that kind of reasoning before.
I did not argue about whether he had been stressed, frightened, or desperate. Those feelings might have been real. They did not explain away the decisions he had made.
I filed for divorce and asked the court to address the financial issues through the proper process.
The affair hurt in ways I could not neatly measure. The photographs showed years of trips and expensive gifts that I had never known about. While I was working late to balance accounts and planning how we might afford fertility treatment, Mason had been building another life.
But the affair was not the only reason our marriage ended.
The deeper break was that he had treated my trust as an asset he could spend.
He had taken my money, my signature, and my grandmother’s house and used them to support a plan I had never agreed to.
When the divorce was finalized, the court addressed the marital financial issues based on the evidence and the applicable law. The house inherited from my grandmother remained mine, and the financial claims arising from the disputed transactions were handled separately from the division of marital assets.
The criminal case also reached a resolution after the evidence was presented and the legal process ran its course. Mason accepted responsibility for specific financial offenses under a negotiated plea agreement, while other allegations were resolved according to the final court record. He was ordered to make restitution for the proven losses and received a sentence that included probation and a period of home confinement.
The outcome was not a cinematic moment in which every wrong was instantly repaired.
The restitution process would take time. The company still had losses to address, and the investigation had left several people facing difficult questions about the controls they had failed to maintain.
But the court had established consequences for the conduct it found proven.
I did not attend every hearing.
I had learned that moving forward did not require me to witness every moment of Mason’s downfall.
I focused instead on rebuilding the parts of my life that had been neglected.
I returned to my work as a senior accountant, eventually taking on a role reviewing internal controls and fraud-prevention procedures. I began setting aside money for myself rather than treating every spare dollar as a contribution to a shared future that only I seemed to be protecting.
I also returned to the small garden my grandmother had planted behind the house.
The first spring after the divorce, the lavender came back along the fence. I spent Saturday mornings pruning it and drinking coffee on the back steps.
For a while, I could not bring myself to use a thermos.
The sight of one reminded me of the morning Mason packed cash, keys, and a flash drive inside a container he had pretended was ordinary.
Eventually, I bought a simple insulated mug.
I filled it with coffee, carried it into the garden, and realized that the object itself had never been the problem.
The secret had been.
One afternoon, Justin stopped by to return a set of documents I had lent him for the case.
“You did the right thing by preserving the files and getting help,” he said. “You didn’t try to become the investigator, the lawyer, and the judge all at once.”
“I wanted to know everything immediately.”
“That’s understandable. But you gave the evidence a chance to speak for itself.”
I thanked him.
After he left, I sat in my grandmother’s kitchen and looked at the framed photograph of her beside the front door.
She had left me that house because she wanted me to have security, not because she expected me to spend my life defending it from the person I married.
For years, I had believed that being a good wife meant trusting Mason even when his explanations didn’t make sense. I thought loyalty required me to give him the benefit of every doubt.
I understand now that trust is not a substitute for evidence, and love is not permission.
I didn’t expose Mason by staging a confrontation or threatening to ruin him.
I preserved the files.
I checked the deed.
I asked a lawyer to protect my property.
I reported what I had found and allowed the relevant authorities to investigate.
The consequences came from the evidence and the decisions he had made, not from revenge.
My marriage ended. The house survived the dispute. My finances took time to repair, and some of the money lost through the scheme could not be recovered immediately.
There were still lonely evenings. There were still moments when I missed the man I had thought Mason was.
But I no longer had to organize my life around the fear that asking a question would make me disloyal.
The last time I saw the empty coffee thermos, it was inside an evidence bag in a photograph attached to a document from the investigation.
It looked ordinary.
That was what stayed with me.
The most dangerous secrets in my marriage had not arrived with dramatic warnings. They had been hidden inside routine expenses, familiar explanations, and a container I had almost ignored.
I had spent years believing that a stable home depended on keeping everything together.
Now I know that stability without honesty is only an appearance.
Mason thought the cash would give him options, the keys would open doors, and the USB drive would keep his records hidden.
Instead, the evidence helped uncover what he had tried to conceal.
And I learned that protecting my future did not require me to destroy his.
It required me to stop sacrificing my own to protect his lies.
The house was still standing.
The garden was growing again.
And for the first time in seven years, every key in my possession belonged to a door I had the right to open.