The Silent Benefactor: The Untold Ledger of Albert Higgins-Part 2
PART 2: The Settlement of Accounts
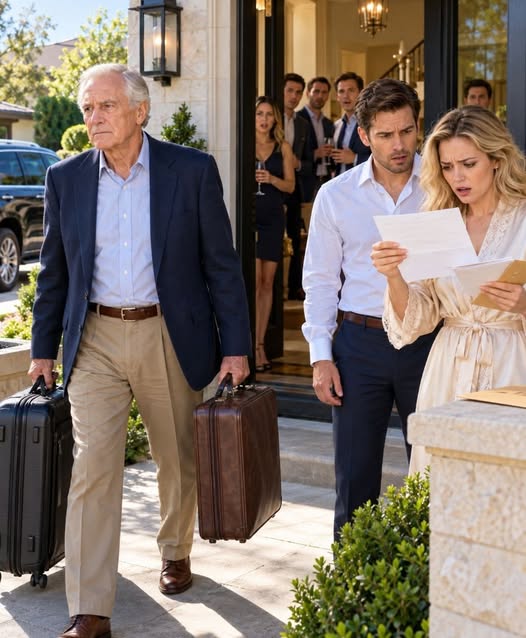
Chelsea stood on the porch as the morning heat began to press down on the concrete, the mug in her right hand forgotten and tilting slightly until lukewarm coffee dripped onto her slippers.
From my car parked fifty yards down the street, beneath the shady canopy of an old live oak, I watched through the windshield. I didn’t feel malice. I felt the precise, cold detachment of a professional reconciling a balance sheet that had been corrupted for far too long.
The three envelopes were not anger; they were reality.
The first letter was from First National Bank of Dallas. For four years, Logan and Chelsea had lived in that five-bedroom house believing they were handling their mortgage like responsible, rising professionals. What Logan had convenient memory loss about—and what Chelsea had never bothered to ask—was that their modest income had failed the debt-to-income stress test during underwriting. I had not merely co-signed the note; I had pledged a collateral account holding $250,000 of my personal funds as a secondary guarantee to secure a favorable, low-interest rate, while quietly setting up an automated transfer that covered 40% of their principal payment every single month under the guise of an “unspecified escrow credit.”
The letter Chelsea held was a formal notice from the bank’s legal department. Following my formal request for total financial disengagement and my removal as guarantor, the lender was exercising its right to reassess the loan parameters. Without my collateral and without my monthly subsidy, the mortgage was immediately flagged for restructuring. Their monthly obligation had just jumped from an affordable $2,100 to an astronomical $5,400, alongside a 90-day cure window to provide new proof of total liquidity.
The second letter was from Silverstone Motors Finance. The high-end SUV Chelsea drove so proudly to her brunches—the one parked so prominently in the driveway—had been leased under a corporate-tier discount program through my credit profile, backed by a personal liability guarantee I had signed when Logan begged me for help during his first year of commission slumps. The notice informed them that the primary guarantor had withdrawn liability. Silverstone was recalling the vehicle within seven days unless the remaining balance of $42,000 was satisfied in full or transferred to an individual account meeting their stringent credit threshold—a threshold neither Logan nor Chelsea met.
The third envelope, however, was the one that truly shattered the fragile facade of their comfortable lifestyle. It came directly from the law offices of Cartwright & Associates. Attached was a notarized Promissory Note and Acknowledgment of Debt, signed by Logan six years ago, two months before my wife passed. It was a document detailing an explicit personal loan of $115,000—money Logan had borrowed to cover a failed business venture in auto detailing that he had hidden from Chelsea and his employers. The terms were unambiguous: Payable upon demand should the lender vacate the co-habitated premises.
I saw Chelsea’s knees buckle slightly. She didn’t finish her coffee. She turned, almost stumbling over her own robe, and rushed back inside the house, slamming the heavy mahogany door so hard the sound echoed down the quiet suburban street.
My phone rang two minutes later.
I didn’t answer.
I looked at the illuminated screen displaying my son’s name—Logan—and placed the phone face down on the passenger seat. I put the car in drive and pulled away from Thunderbird Road, leaving behind the house, the polished quiet, and the illusion that my silence was weakness.
The Dominoes Fall
For the next forty-eight hours, I stayed in my modest, immaculate one-bedroom apartment near downtown Dallas. It had simple hardwood floors, a small kitchen that smelled of fresh coffee, and an unobstructed view of the skyline. It was peaceful.
My phone was a digital war zone.
There were fourteen missed calls from Logan, seven frantic voicemail messages from Chelsea, and dozens of increasingly desperate text messages:
“Dad, please answer. What is this bank letter? There’s been a mistake.”
“Albert, this isn’t funny. You’re threatening our home. We need to talk right now.”
“Dad, call me back. Chelsea is hysterical. The dealership found out about the SUV lease terms. Please.”
On Wednesday afternoon, I instructed Fiona Cartwright that I was ready to meet, but only under controlled terms. I would not argue on a front lawn. I would not debate over dinner tables where I was treated like an inconvenient ghost.
“We meet at my attorney’s office,” I told Fiona. “Thirty minutes. No raised voices.”
When Logan and Chelsea walked into the conference room at Cartwright & Associates on Thursday morning, they looked ten years older than they had on Monday night. Chelsea had dropped her polished, sharp aura. Her eyes were bloodshot, her hair hastily tied back, and the designer dress was replaced by plain jeans and a wrinkled blouse.
Logan looked hollow. He wouldn’t look me in the eye at first; his gaze darted around the conference table, taking in the leather-bound binders, the neat legal pads, and Fiona Cartwright’s composed, unyielding posture.
“Dad…” Logan started, his voice cracking slightly as he pulled out a chair. “Dad, what is all this? We thought… we thought you just went to stay with a friend because you were upset about the party. Why are lawyers sending us default notices?”
I sat across from them, my hands folded neatly over a slim manila folder.
“I didn’t leave because I was upset about the party, Logan,” I said softly, keeping my voice as measured as a bank audit. “I left because the terms of our living arrangement became clear. You asked me to give you space. I am simply giving you total, permanent space.”
Chelsea leaned forward, her composure cracking into sharp anger. “Albert, you can’t do this! You’re sabotaging us! The bank says our mortgage payment is doubling! The finance company is repossessing my car by Monday! Do you have any idea what this is going to do to Logan’s reputation at the dealership? Everyone will know!”
Fiona Cartwright tapped her pen on the desk, a crisp, sharp sound that cut through the room. “Mrs. Higgins, I suggest you adjust your tone. Your husband’s financial standing was built entirely on a foundation of your father-in-law’s credit, liquidity, and personal sacrifice. None of what you enjoyed was stolen from you; it was subsidized by a man you relegated to the back door and side tables.”
“We didn’t know!” Chelsea protested, turning her desperate eyes toward Logan. “Logan, tell her! You never told me your father was paying for half the house! You told me it was a family trust tax structure!”
Logan winced as if he had been struck. He buried his face in his hands. “I… I didn’t want to explain it, Chelsea. When Dad moved in, his name went on the deed to secure the rate. He offered to cover the extra escrow so we could afford the Thunderbird property…”
“He didn’t just cover the extra escrow, Mr. Higgins,” Fiona interjected smoothly, opening a thick document. “Your father paid off your $18,000 credit card debt in 2021. He quietly covered the $12,000 roof repair two years ago when your insurance claim was denied. He paid the property tax supplement every November. Over six years, Mr. Albert Higgins has injected approximately $310,000 of his private liquid funds directly into your household to keep you solvent while you lived well beyond your means.”
Chelsea turned to look at Logan, her expression shifting from panic to sheer disbelief. “Three hundred thousand dollars? You told me your auto business failed clean! You told me we were fine!”
“We were fine!” Logan yelled, his voice breaking as the pressure finally ruptured his calm demeanor. “Because Dad took care of it! He always took care of it!”
“And that was my mistake,” I spoke up, my voice steady, pulling their attention back to the center of the room.
The silence that followed was heavy, suffocating.
I looked directly at my son—the boy I had raised after his mother died, the young man I had tried to shield from every rough edge of the financial world, only to realize I had raised someone who lacked the courage to stand up for the man who built him.
“Logan,” I said quietly. “When your mother passed, I thought protecting you meant taking away every financial worry you had. I thought if I absorbed your debts and paid your bills, you would have the freedom to build a good life. But over the last six years, I watched you change. I watched you look away while your wife treated me like a hired servant in a house my money bought.”
“Dad, I’m sorry,” Logan sobbed, the tears finally overflowing as he reached across the table. “I was stupid. I was stressed about work, I was trying to keep up with Chelsea’s friends, I… I didn’t think it bothered you. I thought you preferred keeping to yourself!”
“There is a difference between preferring solitude and being banished to the kitchen during Thanksgiving,” I replied coldly. “There is a difference between modesty and humiliation.”
“We can fix this, Albert,” Chelsea blurted out, her hands shaking as she reached for the legal documents on the table. “Please. Move back in. We’ll give you the master suite downstairs. I’ll clear out my office. You don’t ever have to use the back door again, I swear to God. Just sign the bank release. If they repossess the car and adjust the mortgage rate, we’ll lose the house within six months!”
I looked at Chelsea for a long moment. I saw the genuine fear in her eyes—not fear of losing me, nor remorse for how she had treated an old man who folded her towels and mowed her lawn—but the cold, sharp horror of losing her status, her social circle, and her aesthetic life.
“I am not moving back, Chelsea,” I said softly. “And I am not signing the releases.”
The Audit of Life
“What are you saying?” Logan asked, his voice barely a whisper. “You’re going to destroy us?”
“No,” I replied, opening the manila folder I had brought with me. “I am going to audit you.”
I pulled out three neatly printed ledgers and pushed them across the table.
“I am retired, but I am still an accountant,” I explained calmly. “I do not believe in ruin out of vengeance. Vengeance is messy, expensive, and emotional. I believe in balance.”
I pointed to the first page.
“The promissory note for $115,000. I am not demanding immediate cash payment today, as I know you do not have it. However, I am placing a formal legal lien against your equity interest in the Thunderbird property. When the bank restructures your mortgage, you will be forced to downsize. When you sell the house, that $115,000 will be paid back to my trust directly from the closing proceeds.”
Logan swallowed hard, staring at his own signature from six years ago. “And… the vehicle?”
“The lease on the SUV will be terminated on Monday,” I continued. “You will surrender the keys to Silverstone Motors. Chelsea, you can drive Logan’s older sedan, or you can purchase a modest used vehicle within your actual financial means.”
Chelsea looked as though she had swallowed glass, but the sharp reality of Fiona Cartwright’s legal presence kept her tongue tied.
“And lastly,” I said, looking at Logan, “my liquid collateral account of $250,000 has been officially moved to an independent private wealth trust managed by Northern Trust Dallas. It is no longer linked to your personal credit. You will have to refinance your remaining mortgage balance independently through a conventional loan. If that means selling the house and moving into a two-bedroom apartment, then that is what you will do. It is time for you to live the life you can actually afford.”
“Dad…” Logan choked out, his voice cracked with shame. “What about us? What about our relationship?”
I stood up, adjusting the cuffs of my jacket. For the first time in six years, my back felt completely straight. The weight of playing the quiet, grateful, silent old pensioner had vanished.
“A relationship built on invisible subsidy and visible disrespect is not a relationship, Logan. It is a commercial arrangement where one party is being exploited,” I said, looking down at him with a mixture of sorrow and finality. “I love you. You are my son, and nothing will ever change that. But I will never again allow myself to be made small so that you can appear large.”
The New Balance Sheet
The weeks that followed were swift and decisive, moving with the cold efficiency of a corporate liquidation.
Without my collateral and monthly subsidies, the reality of Logan and Chelsea’s finances closed in on them like a vise. The SUV was turned in to the dealership on a rainy Tuesday morning; I was told Chelsea wept in the parking lot while Logan signed the turn-in paperwork.
By the end of the second month, the Thunderbird Road house was officially listed on the market. The high interest rates and their restructured debt load meant they could no longer hold the property. They sold it six weeks later in a rushed transaction. After the primary bank paid off the first mortgage and my legal lien of $115,000 was satisfied in full to my trust, Logan and Chelsea walked away with less than $30,000 in liquid equity—just enough to cover the security deposit and first few months’ rent on a modest two-bedroom townhouse on the outer edges of the city.
The news circulated quietly through Logan’s workplace, but not in the way Chelsea had feared. There was no grand scandal—only the quiet, humbling reality that Logan Higgins was no longer the wealthy young executive with an endless safety net. He began working weekends at the dealership, taking extra shifts, taking his job seriously for the first time in his career.
As for me, I settled into my new rhythm.
My $800,000 savings—now fully restored and freed from legal encumbrances, combined with the returned $115,000 loan balance—sat safely inside a conservatively managed high-yield dividend portfolio generating roughly $42,000 a year in passive income, far above my simple pension.
I bought a small, beautiful condo near White Rock Lake. It had a sunlit patio, a modern kitchen, and a spare room that I didn’t turn into a bedroom, but into an office filled with my accounting books, my late wife’s favorite oil paintings, and a grand oak desk.
I joined a local community garden on Tuesday mornings. I took up woodworking on Thursdays. I ate my meals at a full-sized dining table set for one, with proper porcelain plates and warm light, whenever and wherever I pleased.
Six months after that fateful Monday night, my phone rang again. It was a Sunday afternoon.
I picked it up.
“Hello, Logan.”
There was a long pause on the other end of the line. I could hear the faint sound of traffic in the background, a stark contrast to the quiet suburban neighborhood he used to live in.
“Hi, Dad,” Logan said quietly. His voice sounded different—grounded, tired, but remarkably mature. “I… I was just calling to see how you were doing.”
“I’m doing very well, son,” I said honestly. “I just finished planting winter tomatoes on the patio.”
“That sounds nice,” he replied. He cleared his throat. “Look, Dad… I’m not calling to ask for anything. I promise you that. Chelsea and I… we’re adjusting. It’s been hard. We fight sometimes, but we’re going to financial counseling now. I’m paying off my own debt. Every single cent of it.”
“I know you are,” I said softly. “I check the public filings occasionally. You’re doing the hard work, Logan.”
A pause stretched between us, but this time it wasn’t filled with tension or hidden resentment. It was filled with space—the clean, clear space that only honesty can create.
“I was wondering,” Logan said, his voice hesitant, almost vulnerable in a way he hadn’t been since he was twelve years old, “if maybe… I could come over this Sunday? Just me. We could grab a sandwich. Or I could help you move some soil for the garden. Whatever you need.”
I looked out the window of my new home. The Texas sun was setting over the lake, painting the sky in deep shades of gold and amber.
I remembered the quiet dignity of my wife, the years I had spent watching from the background, and the hard lesson that love without boundaries is merely permission for neglect.
“I’d like that, Logan,” I said calmly. “Come by around one o’clock. And don’t worry about bringing anything. I’ll have lunch ready.”
I hung up the phone and placed it neatly on the desk.
In my thirty-five years as an accountant, I had reviewed thousands of financial statements. I had seen massive fortunes built on debt collapse overnight, and I had seen small, modest accounts grow into unbreakable foundations.
It took me sixty-eight years to learn the most important lesson of all:
Money can buy a grand house, expensive dresses, and loud dinner parties that mask the silence in a family’s heart. But respect, dignity, and real love are assets that can never be borrowed, co-signed, or quietly subsidized.
They must be earned, line by line, on a clean ledger.